Case Study: How Liability Umbrella for Retirees Safeguards Retirement Assets
Oct 18, 2026


Key Takeaways
- Liability umbrella policies offer retirees crucial protection against large, unexpected claims that threaten retirement savings.
- Carefully evaluate risks, coverage, and policy features to align supplemental liability protection with your retirement plans.
Retirement should bring security and peace of mind, but new risks may emerge as you protect your lifelong savings. Liability umbrella policies can be a key safeguard. This article explains how these policies work and why savvy retirees are paying attention, culminating in a real case study where one retiree’s proactive planning paid off.
What Is a Liability Umbrella Policy?
Definition and key purpose
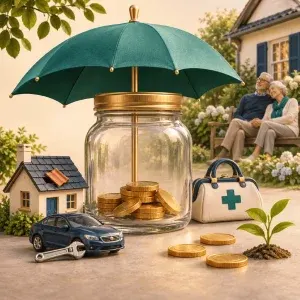
A liability umbrella policy is an extra layer of personal liability insurance that extends coverage beyond the limits of your standard auto, homeowners, or renters insurance. Its main role is to protect you if a significant legal claim exceeds your base policy limits, which could otherwise put your assets at risk.
Who commonly uses these policies
Umbrella liability policies are popular among individuals with substantial savings, such as homeowners, retirees, and anyone wanting to shield assets from legal threats. If you’ve spent decades building retirement funds and acquiring property, these policies can be particularly relevant.
How coverage extends beyond basics
Traditional policies like auto or homeowners offer set amounts of liability coverage. However, high-value lawsuits or settlement costs can quickly exceed those amounts. A liability umbrella picks up where underlying coverage stops, helping to pay for larger claims, legal defense, and settlement costs.
Why Should Retirees Consider Extra Protection?
Risks retirees face with assets
Retirees often have the most to lose in a major lawsuit. If base insurance limits fall short, creditors can target home equity, retirement savings, and other investments to satisfy judgments.
Common scenarios leading to liability
Consider everyday situations: a visitor slips on your walkway, your dog causes injury, or you’re in a multi-car accident. These incidents happen more often than you might believe. If you’re found legally responsible, injured parties may file significant claims.
Consequences of insufficient coverage
If you’re underinsured, the legal system may require you to pay from personal savings, retirement accounts, or even the forced sale of your home. This can quickly derail your retirement plans and create unexpected financial burdens, underscoring the need for comprehensive protection.
How Does a Liability Umbrella Protect Assets?
Coverage in real-life situations
Imagine a home guest sustains an injury and sues for damages far beyond your homeowners policy limits. An umbrella policy may cover liability beyond what your base policy provides, so you don’t have to use your own savings to settle the claim.
Legal cost and settlement protection
Legal defense expenses alone can be daunting, even if you’re found not liable. An umbrella policy can help cover these legal fees, as well as any settlements or judgments, reducing out-of-pocket strain. This support can be crucial during long or complicated lawsuits.
Shielding personal and retirement savings
By stepping in above your primary coverage limits, a liability umbrella can protect what you have worked for. This means your retirement funds, home, and investment accounts stay safeguarded from claims that could otherwise reach into your nest egg.
What Can Happen Without Supplemental Coverage?
Asset exposure in lawsuits
Without a supplemental liability umbrella, a major lawsuit could fully expose your assets. Courts may allow plaintiffs to collect damages from any and all of your financial reserves beyond your insurance limits.
Case examples of uncovered retirees
For example, retirees have lost substantial portions of their savings after accidents involving costly injuries or property damage. In some cases, standard liability insurance caps were quickly reached, leaving the remainder of personal assets vulnerable.
Potential financial setbacks
Such setbacks can emerge rapidly and unexpectedly, disrupting long-term retirement plans. Recovering from these losses can be nearly impossible during retirement, when earning potential is reduced and preserving savings is a top priority.
Case Study: Retiree Safeguards Lifelong Savings
Retiree’s background and concerns
Meet Carol, a recently retired homeowner with a moderate investment portfolio and a focus on leaving a legacy for her family. Her primary concern was protecting her savings from unpredictable legal threats, especially as she began hosting family gatherings more often.
Events leading to liability risk
During one small gathering, a neighbor’s child slipped while playing on Carol’s porch, resulting in a broken arm and a hospital visit. The neighbor’s insurance covered some costs, but the neighbor eventually filed a legal claim for pain, suffering, and long-term care.
How the umbrella policy worked
Carol’s homeowners policy covered medical payments but capped out below the final court settlement. Her existing liability umbrella then kicked in, covering both legal defense costs and the amount beyond her base policy’s limit. As a result, Carol’s retirement accounts and investments remained untouched, allowing her to continue enjoying retirement with financial peace of mind.
Does Liability Umbrella Fit Every Retiree’s Plans?
Factors to consider before choosing
Not every retiree needs a liability umbrella, but it’s important to assess your exposure. Consider your assets, how often you have visitors, and your lifestyle activities. If you have significant savings, own multiple properties, or regularly host guests, additional coverage may be worth it.
Policy limits and exclusions overview
Umbrella policies start where your primary policies end and extend upward. It’s essential to understand potential exclusions—such as certain business activities or intentional acts—which may not be covered by most supplemental policies.
How to align coverage with your needs
Review your overall asset picture, liabilities, and personal risk profile. Determine how extra coverage would interact with your current protections. Consulting a trusted, credentialed professional can help you align coverage choices with your retirement strategy.
Popular posts
Key Takeaways Safe-growth positioning combines growth potential with risk management to protect retirement savings. Regular reviews and diversification are critical to maintaining balanced,
Key Takeaways Conservative investment options can help protect your retirement savings by prioritizing stability and managing risk. Assessing your unique financial needs and consulting a financial professional are key to selecting…
Key Takeaways Safe investment strategies can support financial stability when paired with effective compliance practices. Balancing risk and growth is crucial for protecting and preserving retirement assets in a compliant manner.
Valuable tools to educate yourself – and thrive.
The Certified Safe Money advantage includes access to valuable resources to help you make the right decisions for your retirement goals – because we believe knowledge is power.Browse our current e-books below and prepare yourself for the future.